
News
IVF in transition: 2025 realities and what device manufacturers must do now

FinDBest IVF is a global B2B platform that connects manufacturers of fertility and reproductive health devices with IVF-specialist distributors in over 150 countries. We simplify global expansion, regulatory pathway planning, and distributor onboarding.
Each year, the European Society of Human Reproduction and Embryology (ESHRE) Congress reveals not just clinical updates, but also clear signals about where the IVF market is heading.
In 2025, Circular Communications compiled a focused commercial and product roadmap briefing from the event, kindly shared recently by Dr Georg Griesinger on Linkedin.
What follows is a practical breakdown of their insights—designed for medical device manufacturers and clinical users who need to make fast, evidence-based business and product decisions:
The Six Shifts Reshaping IVF
The IVF landscape in 2025 is not simply evolving—it is undergoing structural change.
Six key forces are reshaping how medical devices are adopted, evaluated, and purchased. Manufacturers who adapt early will find more predictable paths to market.
Those who do not risk falling behind as clinics tighten their criteria.
Cost pressures are now the central constraint
IVF remains financially inaccessible for large segments of the population.
In many countries, patients are still paying out of pocket.
The result is a growing preference for solutions designed around total cost of ownership (TCO).
That means not just upfront purchasing price/cost, but reusability, reliability, throughput, maintenance needs, and training time.
Products that align with capital expenditure (CAPEX) models and flexible subscriptions—especially those matched to clinic cash flow—are more likely to be adopted.
Growth in mature markets has flatlined
In many high-income countries, the number of IVF cycles per capita has plateaued.
For manufacturers, that means growth must now come from share gain or geographic expansion, particularly into fast-growing regions like Southeast Asia, the Middle East and North Africa (MENA), and Latin America.
But entering these markets successfully requires localising value propositions and working with distributors who understand IVF workflows and regulatory constraints.
Legal and ethical oversight is tightening
Questions about embryo selection, long-term storage, and artificial intelligence (AI) in diagnostics are under increased scrutiny.
For manufacturers, this raises the bar on traceability, audit readiness, and labeling compliance.
Products now need to include support for standard operating procedures (SOPs), as well as detailed logging and audit trails.
These are no longer differentiators—they are minimum requirements.
Patient experience has become a key decision factor
Clinics are under pressure to not only deliver outcomes but also reduce the emotional and cognitive burden on patients.
Devices that simplify communication, reduce the number of steps in a procedure, and help patients understand “what’s next” are increasingly favored.
Clear interfaces, intuitive indicators, and minimal user intervention all contribute to better adoption.
Clinic consolidation is shifting how buying decisions are made
Independent clinics are being replaced or absorbed by multi-site groups (Eg. US Fertility or IVIRMA, owned by KKR).
These groups prioritise enterprise-style purchasing: standardised protocols, centralised training, measurable return on investment (ROI), and clear service levels.
Manufacturers that can offer SOP kits, multi-site onboarding, and enterprise-level value metrics will have a distinct advantage.
Technology alone no longer drives differentiation
Automation, AI, microfluidics, smart incubation systems, and digital integration are becoming standard.
The key to winning adoption now lies in reproducibility, data quality, interoperability, and auditability—not just product specifications.
Clinics expect devices that integrate easily with their digital systems and produce consistent results across different settings.
Each of these shifts presents a challenge, but also a roadmap.
Cost, regulation, technology, and buyer behavior are all converging toward a more structured and evidence-driven IVF market.
Manufacturers who address these realities in their design, pricing, and commercial execution will be best positioned to scale.
Clinical and Technological Frontiers Highlighted at ESHRE 2025
Beyond the market dynamics, ESHRE 2025 spotlighted several areas of clinical innovation that are directly shaping device and diagnostics development.
These themes are not theoretical—they are influencing purchasing, adoption, and regulatory expectations now.
Ovarian stimulation protocols are being rethought As clinics aim for personalisation and patient comfort, the need for smarter diagnostics and more flexible drug delivery systems is growing.
Biomarkers that can predict ovarian reserve and treatment response are informing stimulation protocols, making room for devices that adapt to individual profiles.
At the same time, there is a clear trend toward mild stimulation protocols, which create demand for less-invasive monitoring tools and delivery systems that are intuitive, reliable, and easy to train on.
The ongoing refinement of protocols using gonadotropin-releasing hormone (GnRH) antagonists reinforces the need for workflow-agnostic solutions—those that can fit into varying cycles without adding complexity.
Embryo selection is moving well beyond morphology
Objective, evidence-backed methods are replacing subjective scoring.
One major area of interest is AI-supported time-lapse imaging, which offers the potential to assess embryo viability in a more standardised and reproducible way.
However, clinics are demanding validated tools—classified appropriately as software as a medical device (SaMD), with integration capabilities and clean clinical evidence.
In parallel, non-invasive preimplantation genetic testing (niPGT) is gaining momentum.
Media capable of capturing cell-free DNA (cfDNA), paired with ultra-sensitive genetic testing platforms, could redefine embryo selection workflows.
This is not a future trend—it’s a present R&D priority.
Manufacturers need to plan both the evidence and regulatory strategy from the outset.
Metabolomics and biomarker analysis of culture media are also being explored, particularly where kits can offer clear utility and fit easily into existing lab infrastructure.
Implantation remains a key bottleneck
Even with viable embryos, successful transfer remains challenging.
There is growing interest in non-invasive endometrial diagnostics that can assess uterine receptivity without disrupting workflow.
The market demands tools that are specific, reproducible, and easy to use.
Meanwhile, catheter design continues to influence both outcomes and patient experience.
Ergonomics, atraumatic placement, and consistent delivery are still core drivers of successful transfers.
While less discussed in marketing, this area remains a top priority for clinical users and therefore deserves more innovation attention.
Taken together, these frontiers point toward a product development path that favors integration over novelty, reproducibility over experimentation, and real-world usability over theoretical performance.
It is not just what your device does—it is how it fits into the day-to-day life of clinics under pressure.
Regulatory and Market Access: Build It In, Not On
Global regulatory expectations are rising, and shortcuts are closing.
Product teams can no longer afford to treat compliance as a post-development task. It must be embedded from Day 0.
For software and AI-based tools, classification is tightening across the United States, European Union, and China.
This means developers must create full validation plans early, align endpoints with regulatory expectations, and document cybersecurity and data governance practices before launch.
Post-market surveillance and post-market clinical follow-up are not optional; they need to be built into the development process.
Culture media and reagent products are under increased scrutiny from regulations like the European Union’s Medical Device Regulation (MDR) and In Vitro Diagnostic Regulation (IVDR).
Manufacturers must establish robust quality systems, ensure all labeling is complete and language-appropriate, and be ready to implement unique device identification requirements in every target market.
For connected lab devices, regulatory bodies expect more than just functionality.
They now require detailed documentation of data interoperability, security protocols, and integration capabilities.
Manufacturers should design clean application programming interfaces (APIs) and seamless connectors for hospital and laboratory data systems to make compliance easier—not harder—for clinics.
A practical checklist for manufacturers:
- Confirm software classification and plan validation early for each market.
- Create templates for traceability, labeling, audit logs, and PMS/PMCF.
- Implement cybersecurity and data protection frameworks from Day 0.
- Ensure unique device identification (UDI) compliance for each geography.
- Offer clear integration documents for lab systems (no assumptions).
Strategic Focus Areas for IVF Device and Diagnostics Manufacturers
- Balance cost and innovation
Demonstrate lower total cost of ownership through real-world data. Show how your product reduces maintenance, training time, or consumable use. - Support with evidence, not claims
Build prospective, multi-site clinical studies. Prepare audit-ready documentation: instructions for use, labeling, traceability, and surveillance templates. - Integrate digital and physical
Provide open, secure APIs. Ensure fast and simple onboarding for embryologists and nurses. Focus on reducing clicks, errors, and delays. - Refine embryo selection strategy
Align product claims with validated inputs—whether AI models, cfDNA media, or metabolomic markers. Monitor data drift and revalidate regularly. - Improve uterine receptivity and transfer tools
Support claims with performance data (e.g. time to placement, consistency). Offer quick training modules to accelerate adoption. - Embed regulatory design
Maintain a live matrix of requirements per SKU and market. Don’t delay planning for UDI, cybersecurity, PMS/PMCF. - Sell to enterprise buyers
Offer group-level SOP kits, ROI calculators, and centralised onboarding. Provide remote diagnostics and clear SLAs to reduce downtime. - Speed up market entry through smarter distribution
Use IVF-experienced distributors with proven regulatory capabilities. Shorten time to first order by removing the guesswork.
Key Takeaways
- Total cost of ownership is now the key metric—design around it.
- Patient workflows and clinic processes must be simplified.
- Reproducibility and integration matter more than specs.
- Plan evidence generation around the claims you want to make.
- Prepare for audits with full traceability and post-market tools.
- Offer group-ready commercial packages for multi-site chains.
- Match each market with a localised regulatory strategy.
- Choose distributors who understand both IVF and compliance.
FinDBest IVF: Your Partner in Global Expansion
These insights from ESHRE 2025, as compiled by Circular Communications, offer a compelling glimpse into the future of fertility treatment.
For medical device manufacturers, these trends are direct signals for where to focus R&D, innovation, and market entry efforts.
At FinDBest IVF, we specialise in helping medical device manufacturers navigate the complex global regulatory landscape.
Whether you’re developing cutting-edge AI for embryo selection, next-generation culture media, or advanced cryopreservation devices, we can help you:
- Find regulatory-savvy distributors and license holders.
- Identify partners who understand country-specific timelines and dossier formats.
- Expand globally, faster — with fewer surprises.
Credits
- Original, full report by Circular Communications
- Shared on Linkedin by Georg Griesinger







The UK government is reviewing a surrogacy firm after complaints that medical insurance claims involving surrogates in Mexico were rejected.
The Department of Health and Social Care (DHSC) is considering whether UK-based provider My Surrogacy Journey should remain listed on gov.uk as one of four domestic surrogacy agencies available to intended parents.
The review follows allegations concerning its Mexican sister company, where surrogates are based.
Health minister Diana Johnson said: “The department is looking into the allegations about My Surrogacy Journey.
“As part of that assessment, the department will consider whether it is appropriate for that company to remain on the gov.uk list of agencies.”
Emails sent by My Surrogacy Journey chief executive Michael Johnson-Ellis and seen by the Guardian suggest multiple surrogate women in Mexico had their insurance claims rejected.
The emails also suggest 300 couples using the company were moved to a new insurance provider because of the increased risk of claims being rejected.
Commercial surrogacy is banned in the UK, where only altruistic arrangements are permitted.
My Surrogacy Journey operates a not-for-profit UK branch alongside for-profit sister companies in Mexico and the US. All three companies have the same owners and chief executives.
The reported insurance issues relate to surrogacy arrangements in Mexico.
One couple told the Guardian they paid tens of thousands of pounds to cover medical costs after their surrogate had a hysterectomy during childbirth and an insurance claim was refused.
The Guardian said it understood that at least five sets of parents said they had to cover medical costs after insurance claims were rejected.
In an email to the couple whose surrogate underwent a hysterectomy, Johnson-Ellis wrote: “We have already told you that the insurance companies have been declining some of the claims and we are actively working with the broker to get this issue resolved but you should also consider that they may not be paid out and there is nothing we are able to do to change this …
“We appreciate this is not an insignificant sum but this genuinely is out of our control.”
Johnson-Ellis also said the company had switched insurance providers, writing: “We’re also managing this for 300 other journeys, which is a complex position to be in.”
Lawyers acting for My Surrogacy Journey said the company did not comment on individual cases, but that existing insurance policies were in place and claims continued to be accepted and processed.
They said the company understood that a small number of claims had been rejected and was supporting people seeking to resolve those claims with an insurer.
Under the surrogacy arrangements, intended parents are understood to be contractually required to cover medical costs not paid by an insurer.
The couple said they had been recommended the company’s Mexico option. Its website advertises that intended parents using the route can have a baby in “under 18 months”.
They said they were told the UK route could take up to five years and that the US option was much more expensive.
Lawyers for My Surrogacy Journey said prospective parents are given information about typical timelines, costs, legal frameworks and practical considerations, and that the 18-month timeframe is indicative only.
The couple said their surrogate developed placenta accreta, a serious condition in which the placenta attaches to the wall of the uterus.
Emails from Johnson-Ellis acknowledged that the insurance provider investigated the birth after the surrogate experienced health complications.
The parents are considering legal action, while the Guardian said it understood at least four other couples were reviewing their options.
Phil Brickell, MP for Bolton West, raised concerns in parliament about a separate couple who had used My Surrogacy Journey.
He said: “Two of my constituents recently travelled to Mexico, where their children were born by surrogacy.
“Those births were facilitated by a company called My Surrogacy Journey, which is listed on gov.uk.
“While in Mexico, they had repeated traumatic experiences with the company relating to issues including insurance for their children, accusations of bullying towards staff and repeated efforts to silence any constructive criticism.
“I understand that other members of this house have received similar complaints.”
Brickell called for My Surrogacy Journey to be removed from gov.uk pending a review by the Human Fertilisation and Embryology Authority.
Lawyers acting for My Surrogacy Journey said the company was communicating with DHSC and was confident any issues could be resolved.
Many menopause supplements contain ingredients with limited evidence for symptom relief, while formulations and prices vary widely, a study has found.
Researchers analysed 201 products sold by nine major UK retailers, comparing their ingredients, doses and monthly costs.
Prices ranged from £1.50 to £95 a month, while no single ingredient or category of ingredient was common across all products.
The study, carried out by University College London, found that 80 per cent of products contained herbs, 77 per cent contained vitamins and 74 per cent contained phytoestrogens, naturally occurring plant compounds found in foods including soy and flaxseed.
Vitamin B6 was the most common vitamin, while red clover and sage were the most frequently identified plant ingredients.
Researchers said more evidence was needed on the effectiveness and safety of supplements marketed for menopause symptoms.
Professor Joyce Harper, senior author of the study and professor of reproductive science at University College London, said: “The menopause supplement market is growing rapidly, despite limited scientific evidence that many of these products improve menopause symptoms.
“Some social media influencers promote these products as effective solutions, despite many claims not being supported by scientific evidence.
“This can contribute to the spread of misinformation and help drive a rapidly growing menopause supplement market, leading some women to spend substantial amounts of money on supplements in the hope of improving their symptoms and overall wellbeing.”
Half of the supplements did not contain vitamin D, while less than 24 per cent contained calcium.
The British Menopause Society and International Menopause Society have highlighted vitamin D and calcium as important for maintaining bone health and preventing osteoporosis after menopause.
Researchers also identified botanical ingredients that may carry risks, including black cohosh.
Poppy Sullivan, first author of the study, said: “Certain botanical ingredients in some menopause supplements may also have risks.
“Black cohosh, in particular, is known to carry a potential risk of liver toxicity.”
The amounts of vitamins and minerals included in different products also varied widely.
Sullivan said: “Some nutrients can have adverse effects when consumed in excess over time.
“For example, excessive vitamin D intake can theoretically lead to high calcium levels, which could cause adverse effects such as vomiting and confusion.”
The study found little empirical evidence supporting the effectiveness of even the most expensive products.
Researchers called for more high-quality research, including clinical trials, to determine whether menopause supplement ingredients are effective and safe.
They said the findings could also help healthcare professionals understand the wide variation in supplement formulations.
The researchers acknowledged that the analysis may not have included every menopause supplement available in the UK.
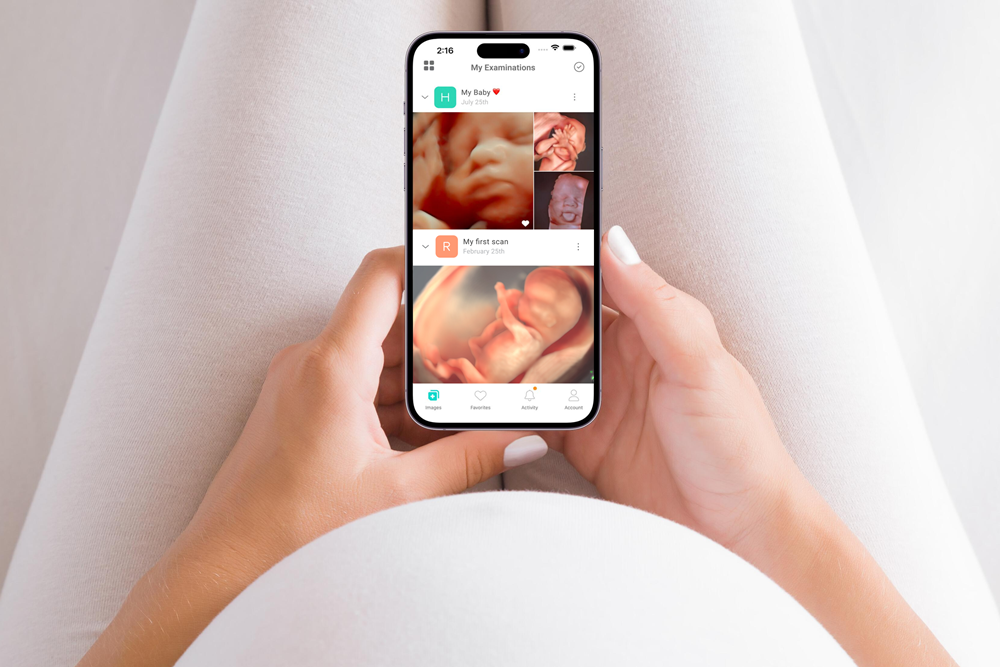
Ultrasound Direct has extended its Trice Imaging partnership for three years, adding a reporting tool across its 70-clinic UK network.
The private ultrasound provider will continue using the Tricefy platform for secure image storage and patient engagement, alongside TriceIQ for efficiency and productivity analytics.
It will also introduce Trice Workspace Reporting across its network. The companies say the tool will help standardise ultrasound reporting templates and workflows and reduce variation between clinics.
Ultrasound Direct carries out an estimated 120,000 patient scans each year across services including pregnancy, fertility, women’s health, men’s health and other diagnostic pathways.
Its network uses a large pool of sonographers working across different ultrasound systems and serves referral routes including self-referring patients, GPs and commercial partners.
Mike Steward, founding director at Ultrasound Direct, said: “Having worked with Trice Imaging since 2018, we first partnered to replace manual methods of providing scan images to expectant parents with Trice’s secure electronic image-sharing platform. Today, every study performed across the Ultrasound Direct Network is recorded and stored on Tricefy, while our clinical services have expanded considerably beyond pregnancy into fertility, women’s health, men’s health and other diagnostic pathways.”
He added: “To continue futureproofing our image management strategy across a network of 70 clinics, a large team of sonographers, varying ultrasound systems and a growing number of referral partners with different needs, we decided to extend with Trice Imaging. This includes the introduction of the new Trice Workspace Reporting module to help us scale and standardise our ultrasound reporting templates and workflow, reducing variability between clinics.”
The partnership began in 2018, initially focusing on replacing manual methods of sharing pregnancy scan images with expectant parents.
Johanna Wollert Melin, founder and chief executive of Trice Imaging Europe, said: “Ultrasound Direct has been a valued partner in the UK for 8 years.”
She added: “At the heart of the relationship is a willingness to explore new ideas, test new tools and the spirit to solve real challenges across a large and complex clinical network.”
Mark A. Samii, chief revenue officer at Trice Imaging, said: “We are delighted to retain and extend our relationship with Ultrasound Direct.”
He added: “The addition of Trice Workspace Reporting addresses a challenge we hear from multi-site providers globally – keeping reporting quality consistent across many users, systems, referral or payer relationships.”
Steward said Ultrasound Direct continues to see growing demand for private diagnostics alongside NHS care from self-referring patients and an increasingly diverse range of professional and commercial referral partners.
He added: “As that development continues, scalable digital infrastructure becomes increasingly important. Our focus is on ensuring that a growing national network can support consistent clinical workflows, different referral pathways and the technology requirements of the future, while continuing to provide patients with accessible diagnostic services.”




 Entrepreneur1 week ago
KOVE Medical raises €1.7 million to improve safety of foetal surgery
 Pregnancy1 week ago
UK study aims to transform maternity care for high-risk pregnancies
 Fertility1 day ago
Paracetamol use may impact future fertility, studies suggest
 Entrepreneur4 days ago
Last chance to save on Women’s Health Week and Women’s Sport Summit: Early Bird pricing ends 11 September
 Mental health2 weeks ago
PMDD after SSRIs or hormones: Why the brain may be the missing treatment target
 Diagnosis2 weeks ago
Ark Surgical secures further institutional backing to accelerate US expansion
 Menopause1 week ago
Menopause hormone treatment may ease brain fog, study suggests
 Motherhood2 weeks ago
Thousands of UK women develop undiagnosed PTSD after childbirth each year – study